Why does a Trailhunter 1000 cost roughly $2,500 less than a comparable Japanese ATV, yet $1,800 more than a Chinese-built equivalent with similar displacement? If you ask a SWM dealer, they’ll talk about Italian design heritage and European component sourcing. If you ask a competitor, they’ll mutter about predatory pricing. The truth — as it usually does — sits somewhere in the middle, and it reveals a deliberately engineered pricing architecture that is far more strategic than either narrative suggests.
Let’s start with the cost structure that makes the numbers work. SWM operates a dual-continent manufacturing model: vehicle assembly happens in China at a facility that achieves labor costs roughly 40% below the European average, while R&D, design, and quality engineering remain anchored in Milan. This split allows SWM to capture roughly 60-65% of the manufacturing cost advantage that a pure-Chinese OEM enjoys, while retaining the utv 1000cc standards and design language that justify a premium over no-name competitors. It’s not magic — it’s geography arbitrage applied to industrial production.
The Competitive Price Map
| Brand | 1000cc ATV MSRP (USD) | Manufacturing Base | R&D Center | Warranty Coverage |
|---|---|---|---|---|
| Japanese Brand A | $14,200 – $16,800 | Japan / USA | Japan | 12 months |
| Japanese Brand B | $13,500 – $15,900 | Japan / Thailand | Japan | 12 months |
| SWM Trailhunter 1000 | $11,200 – $12,500 | China (assembly) / Italy (R&D) | Italy | 24 months |
| Chinese Brand C | $8,900 – $10,200 | China | China | 6-12 months |
| Chinese Brand D | $9,500 – $11,000 | China | China | 12 months |
The gap between SWM and the Japanese incumbents is immediately visible — roughly 18-22% cheaper at the MSRP level. But the gap between SWM and the Chinese challengers is equally instructive: approximately 18-25% more expensive. SWM has positioned itself in what pricing strategists call the “value premium” zone — above the price-war territory where Chinese brands compete on cost alone, but below the established tier where Japanese manufacturers charge for decades of brand equity and dealer network density.
This positioning is deliberate and defensible for three reasons. First, the hybrid side by side infrastructure — 24-month warranty, 24/72-hour parts response, and the Smart Rider diagnostic ecosystem — creates a total cost of ownership argument that partially offsets the sticker premium over Chinese alternatives. A fleet buyer doing a three-year TCO calculation will find the SWM within 8-12% of a Chinese competitor once warranty claims, downtime, and residual value are factored in. Second, the Italian design story provides a brand narrative that Chinese challengers cannot replicate — and in markets where powersports buyers are brand-conscious, that narrative has measurable value. Third, the mid-market positioning gives SWM room to move in both directions: they can discount selectively to defend against Chinese price pressure without destroying margins, or add premium features to justify moving upmarket against the Japanese.
There’s a subtler layer to this strategy that most analysts miss. SWM’s pricing isn’t uniform globally — it follows a market-by-market elasticity model. In Southeast Asia, where Chinese competitors are entrenched and price sensitivity is extreme, SWM prices closer to parity. In Europe and North America, where the Italian heritage carries more weight and buyers are less price-sensitive, the premium is wider. This isn’t inconsistency; it’s sophisticated price discrimination enabled by a manufacturing cost base flexible enough to support variable margins across regions.
- SWM’s pricing sweet spot: 18-22% below Japanese, 18-25% above Chinese competitors
- Key cost advantage: China assembly + Italy R&D = 60-65% of Chinese OEM cost advantage
- TCO argument: 24-month warranty and parts responsiveness narrow the gap to Chinese rivals to 8-12%
- Strategic flexibility: Mid-market position allows both upward and downward movement

One more dimension worth examining is the residual value equation. Early data from North American auction houses and dealer trade-in records suggests that two-year-old SWM units are retaining roughly 62-68% of MSRP, compared to 70-75% for Japanese equivalents and 45-52% for Chinese competitors. This places SWM squarely in the middle of the depreciation curve — not class-leading, but substantially better than the bargain-tier alternatives. For buyers who trade every three to four years, that residual advantage can offset much of the initial premium over a Chinese machine, effectively making the SWM cheaper on a net cost basis over a typical ownership cycle.
Will this positioning hold as Chinese brands improve their quality and Japanese brands lower their prices? The answer depends on whether SWM can continue to widen the moat — not through pricing, but through the intangible assets that justify it: design credibility, dealer support quality, and the ownership experience that turns a transaction into a relationship. The price tag gets them in the door. Everything else keeps them from walking out.
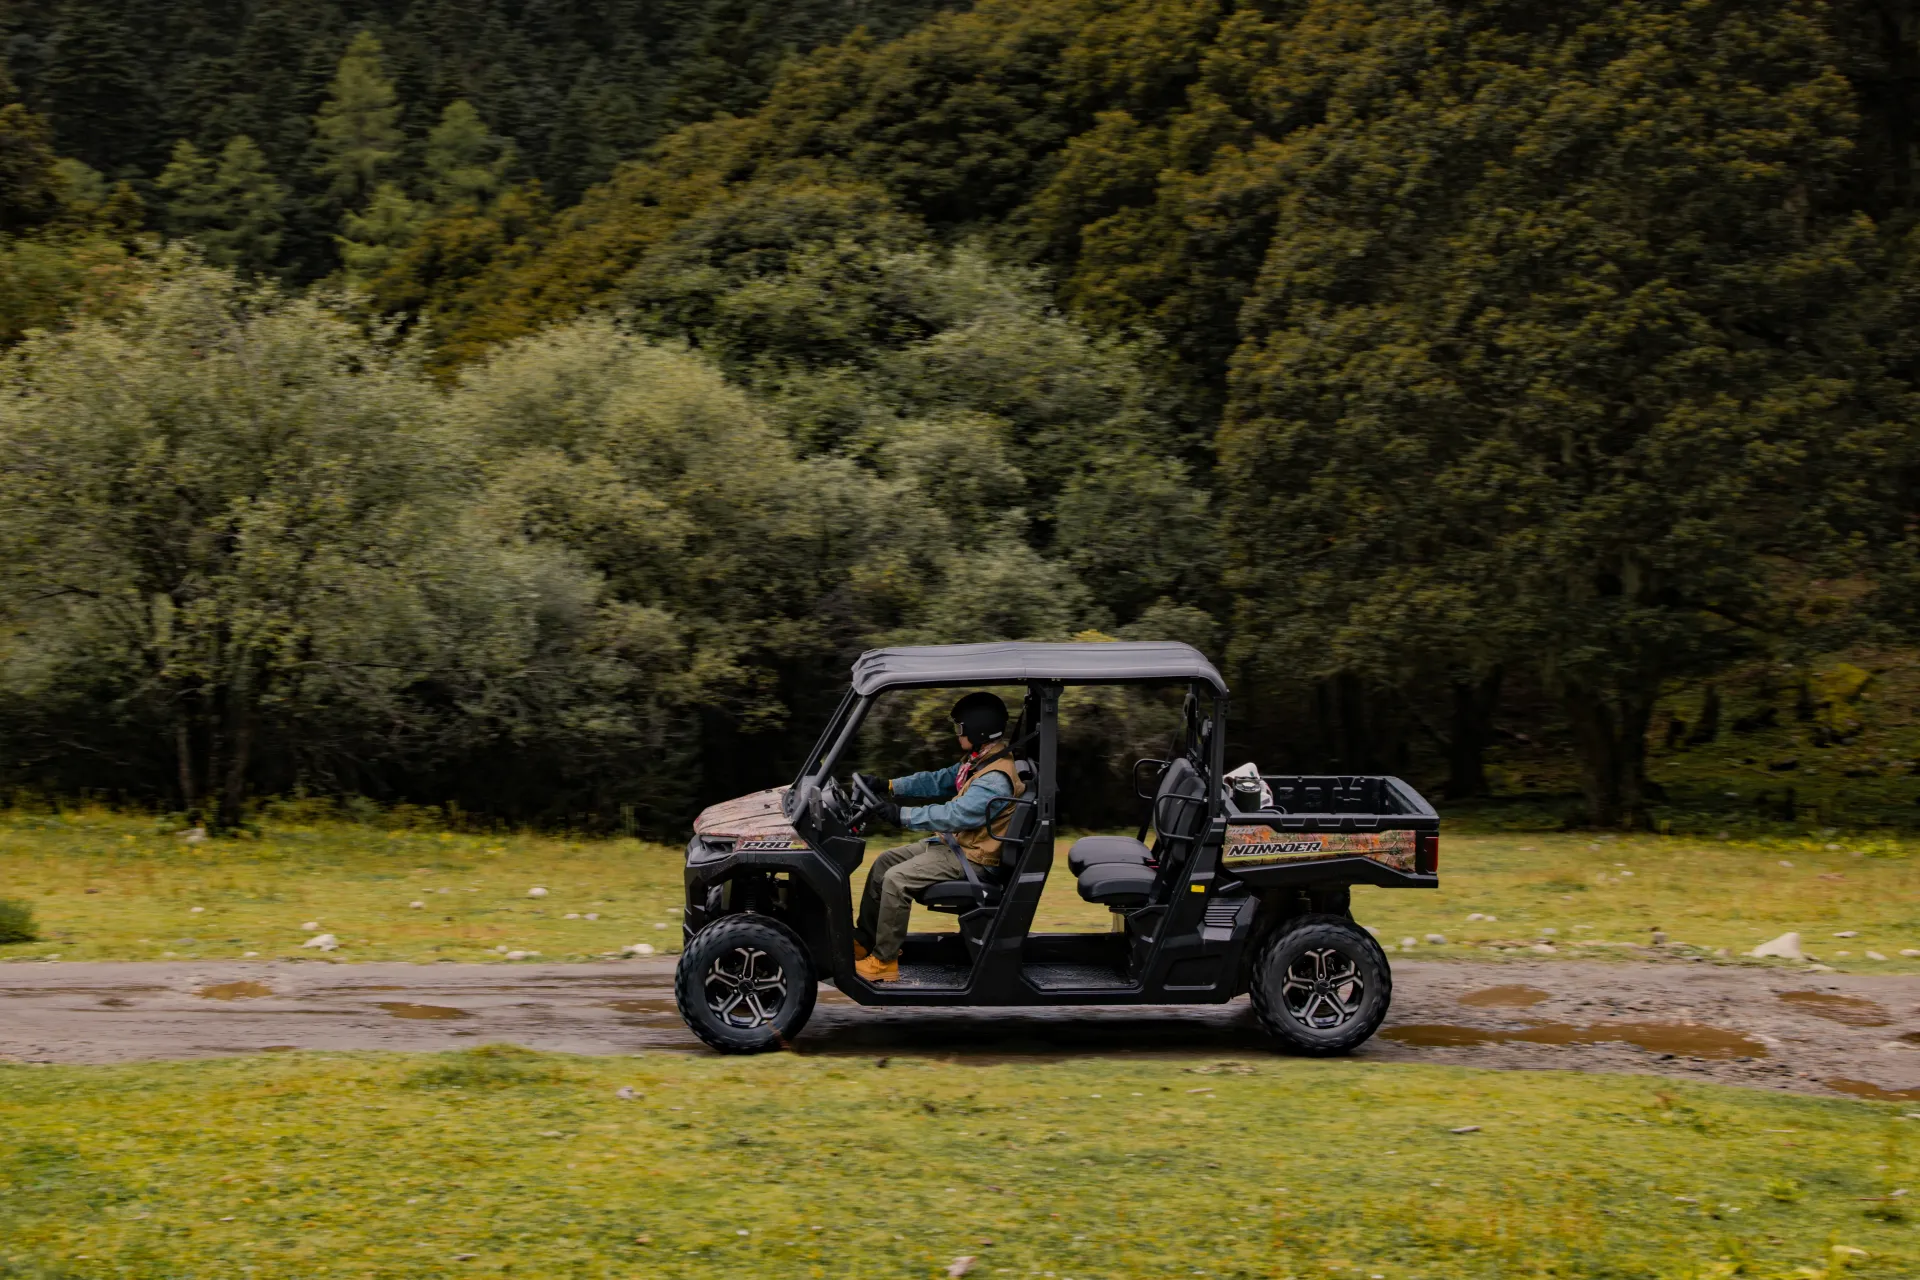
A forward-looking dimension of SWM’s pricing architecture concerns the trajectory of manufacturing-cost convergence between Chinese and ASEAN production bases. SWM’s current cost advantage derives partly from the labor-cost differential between its Chinese assembly facility and Japanese or European alternatives — approximately 40 percent lower direct labor costs. However, Chinese manufacturing wages have been rising at approximately 8 to 12 percent annually for the past decade, and this trend is expected to continue as China’s economy transitions from export-driven manufacturing to domestic consumption. If this wage-growth trajectory persists, the labor-cost advantage that currently supports SWM’s mid-market pricing position could narrow significantly within five to seven years. SWM’s strategic response — already visible in its utv 1000cc supply-chain investments — involves a gradual shift of assembly operations toward Southeast Asian facilities in Thailand and Vietnam, where labor costs remain lower and are projected to stay competitive through 2035. This geographic diversification of manufacturing is not just a supply-chain resilience play — it is a long-term cost-structure hedge against the macroeconomic trends that will reshape global manufacturing competitiveness over the next decade. The brands that are positioning their manufacturing footprints today for the cost structures of 2030 are the ones whose pricing architectures will remain defensible when the current cost advantages begin to erode.